Where: Cash Recognition in the menu. Before you start: have the bank statements for the trust and, for differences, your own transfer record to hand.
Two kinds of record wait for you under Cash Recognition:
  • Fund Manager / Trust Transfer — the fund manager says a different amount arrived than you logged: more, for example because the bank added interest, or less, closed without keeping the rest as an outstanding receipt, for example because of bank charges.
  • Fund Manager Return — the fund manager has sent money back to the trust.
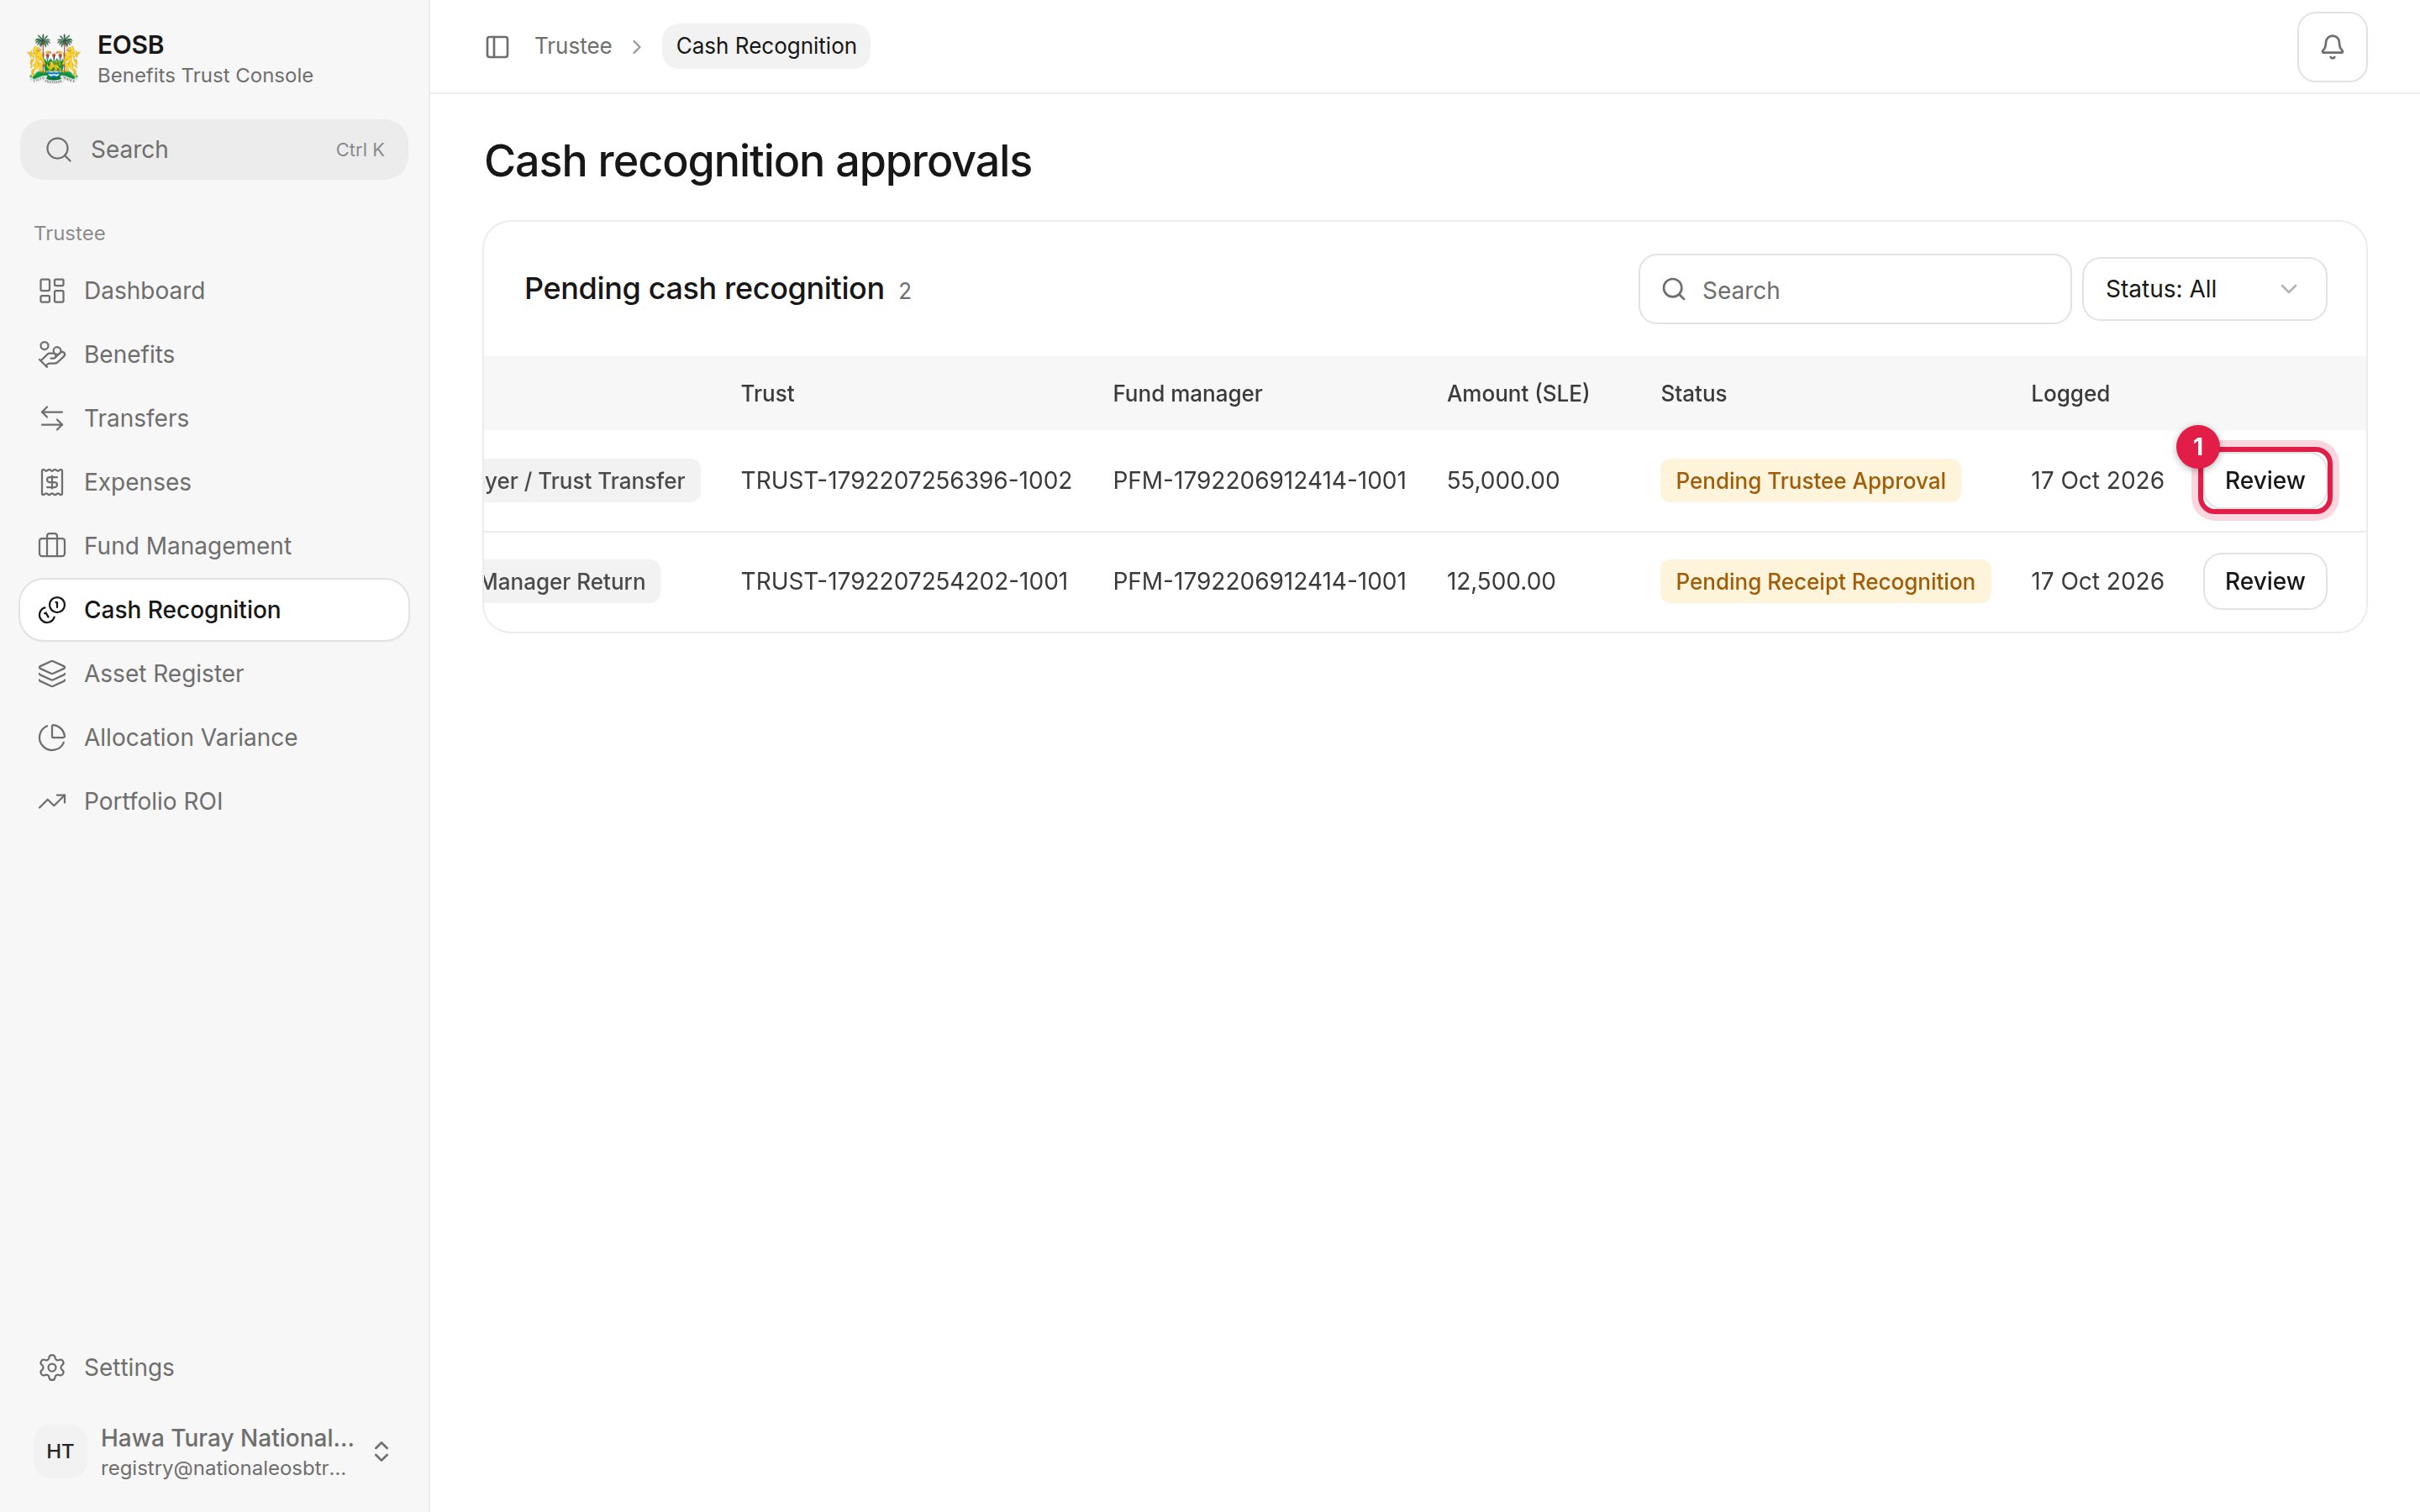
Pending cash recognition: a trust transfer pending trustee approval and a fund manager return pending receipt recognition, with Review marked 1

Waiting for the trustee

Select Review (1) to open a record.

A recognition that differs from what you sent
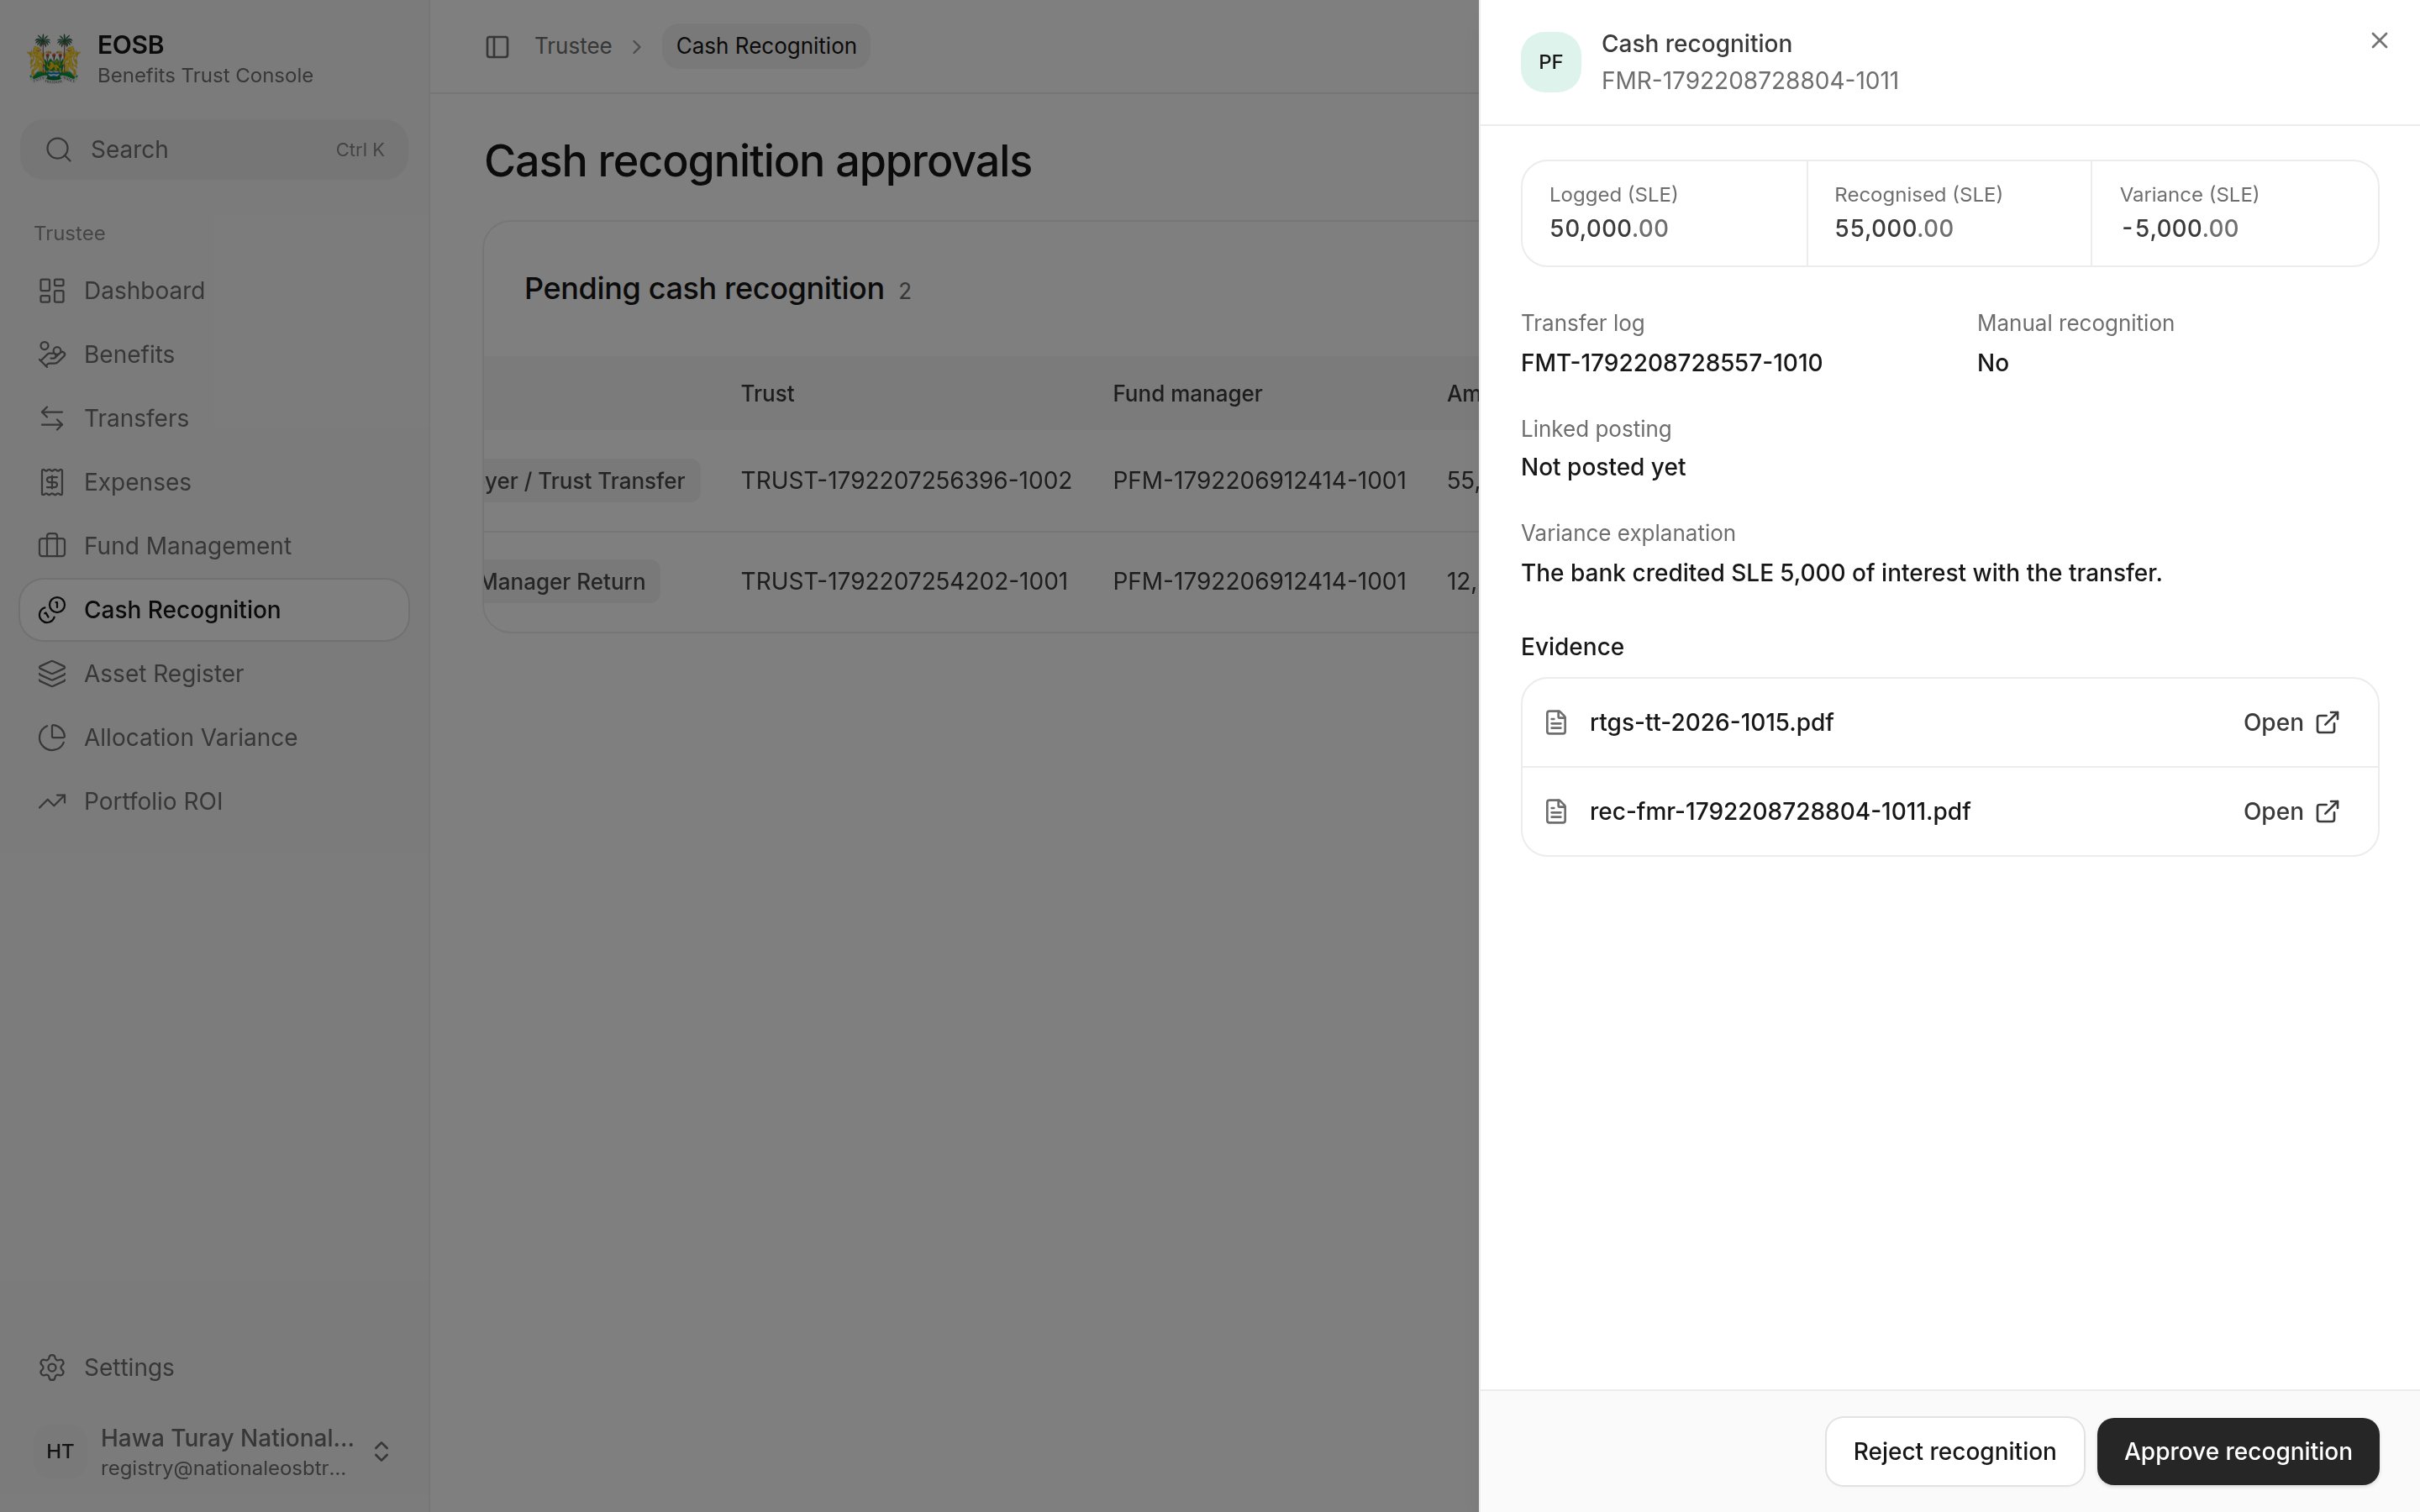
Cash recognition: logged 50,000, recognised 55,000, variance, transfer log, variance explanation and evidence

Cash recognition

Compare Logged and Recognised. Variance is recognised minus logged: positive when more arrived, negative when less did. Read the Variance explanation and open the evidence. Then select Approve recognition (with an optional note) or Reject recognition (with a reason, required).
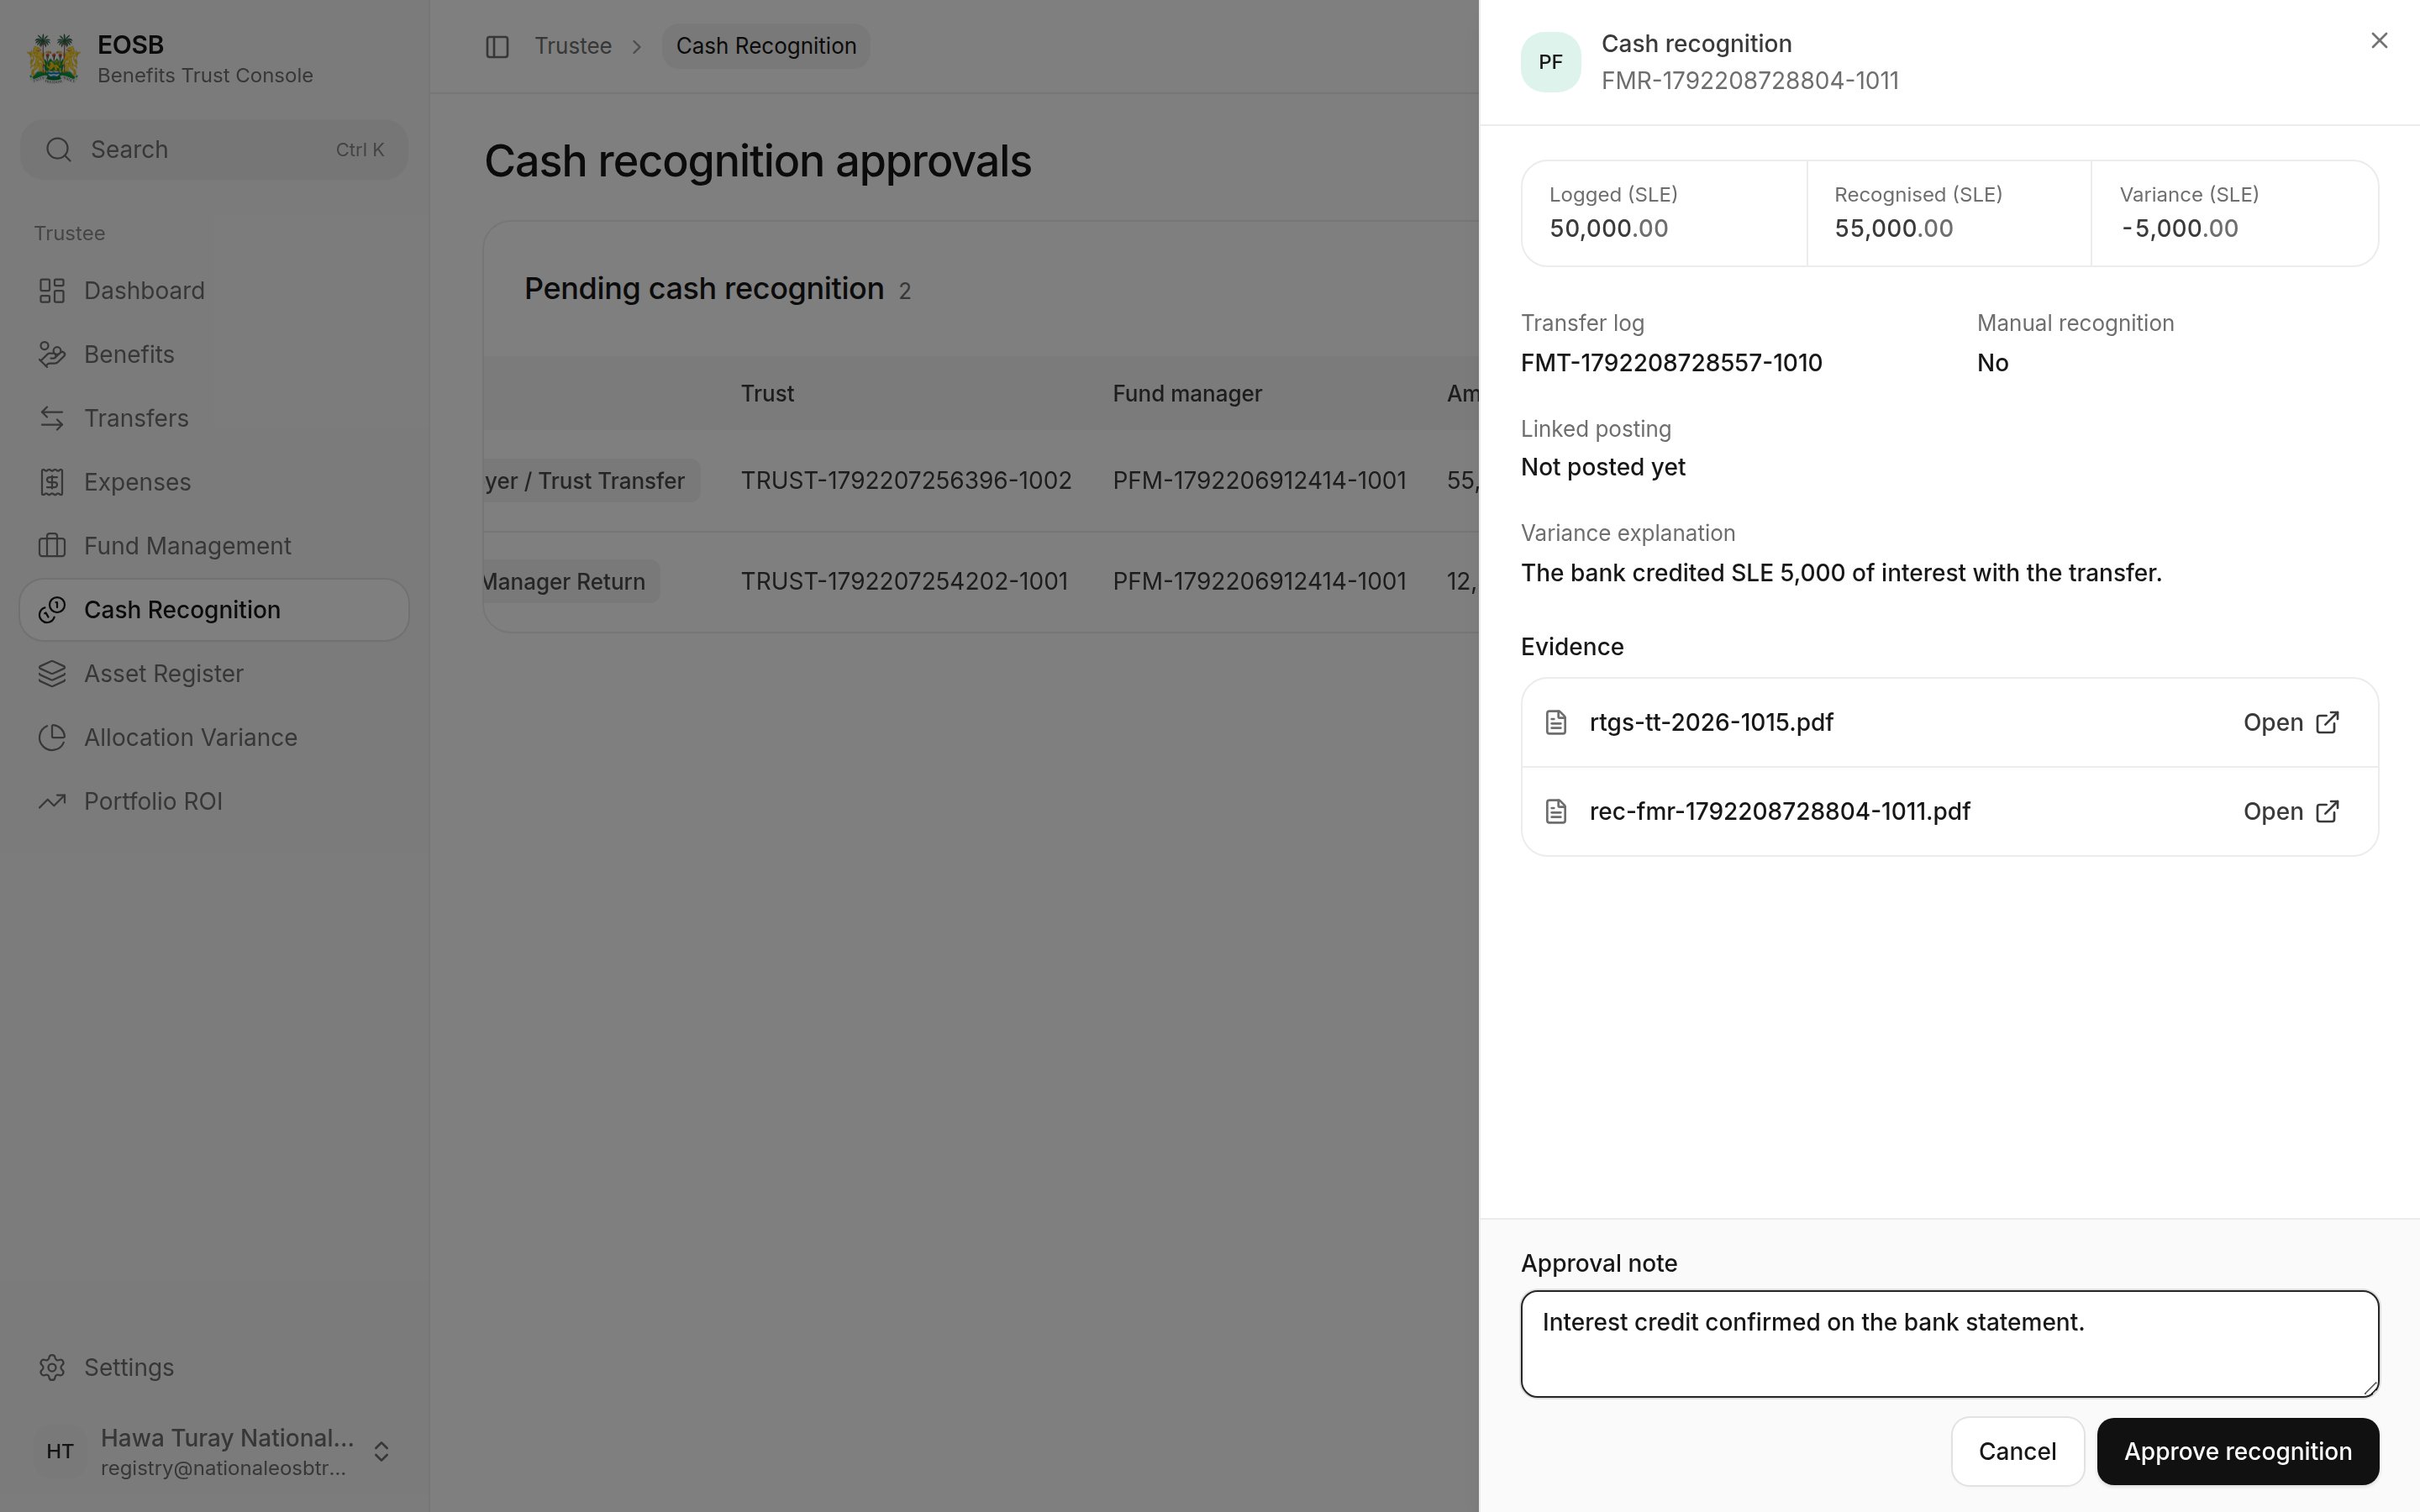
Approval note: Interest credit confirmed on the bank statement, and Approve recognition

Approving with a note

Cash returned to the trust
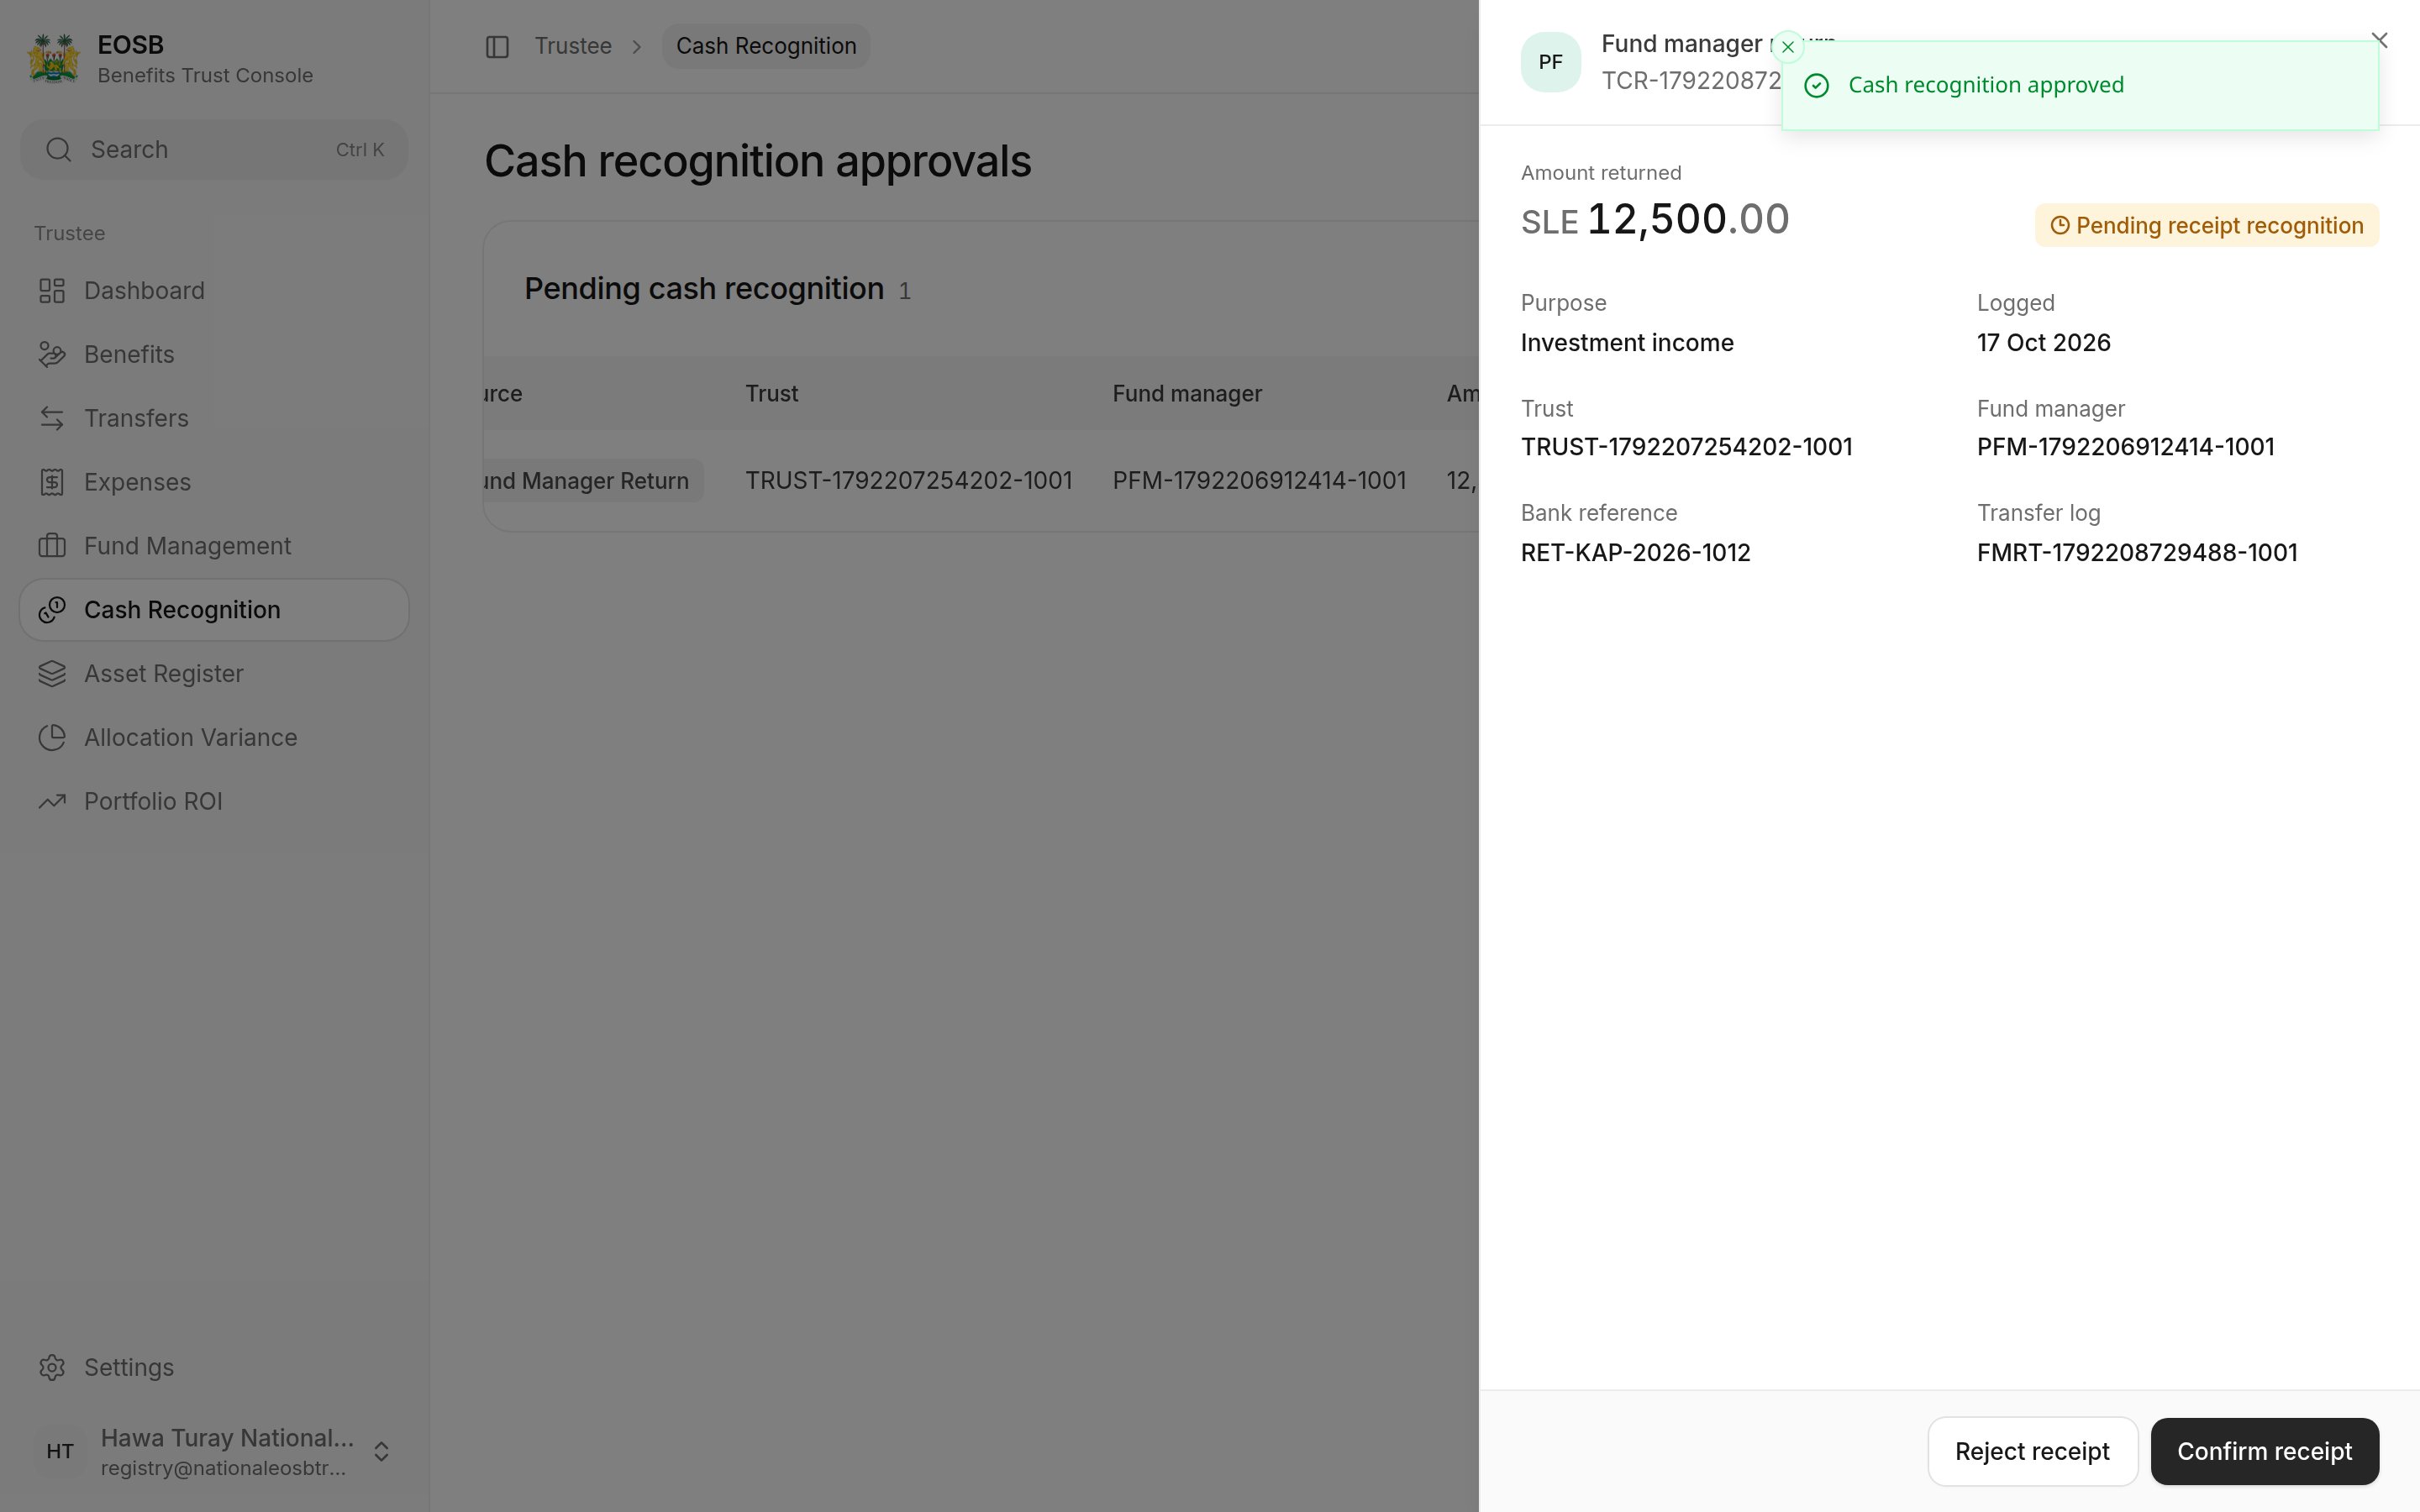
Fund manager return of SLE 12,500 for investment income, with trust, fund manager, bank reference and transfer log
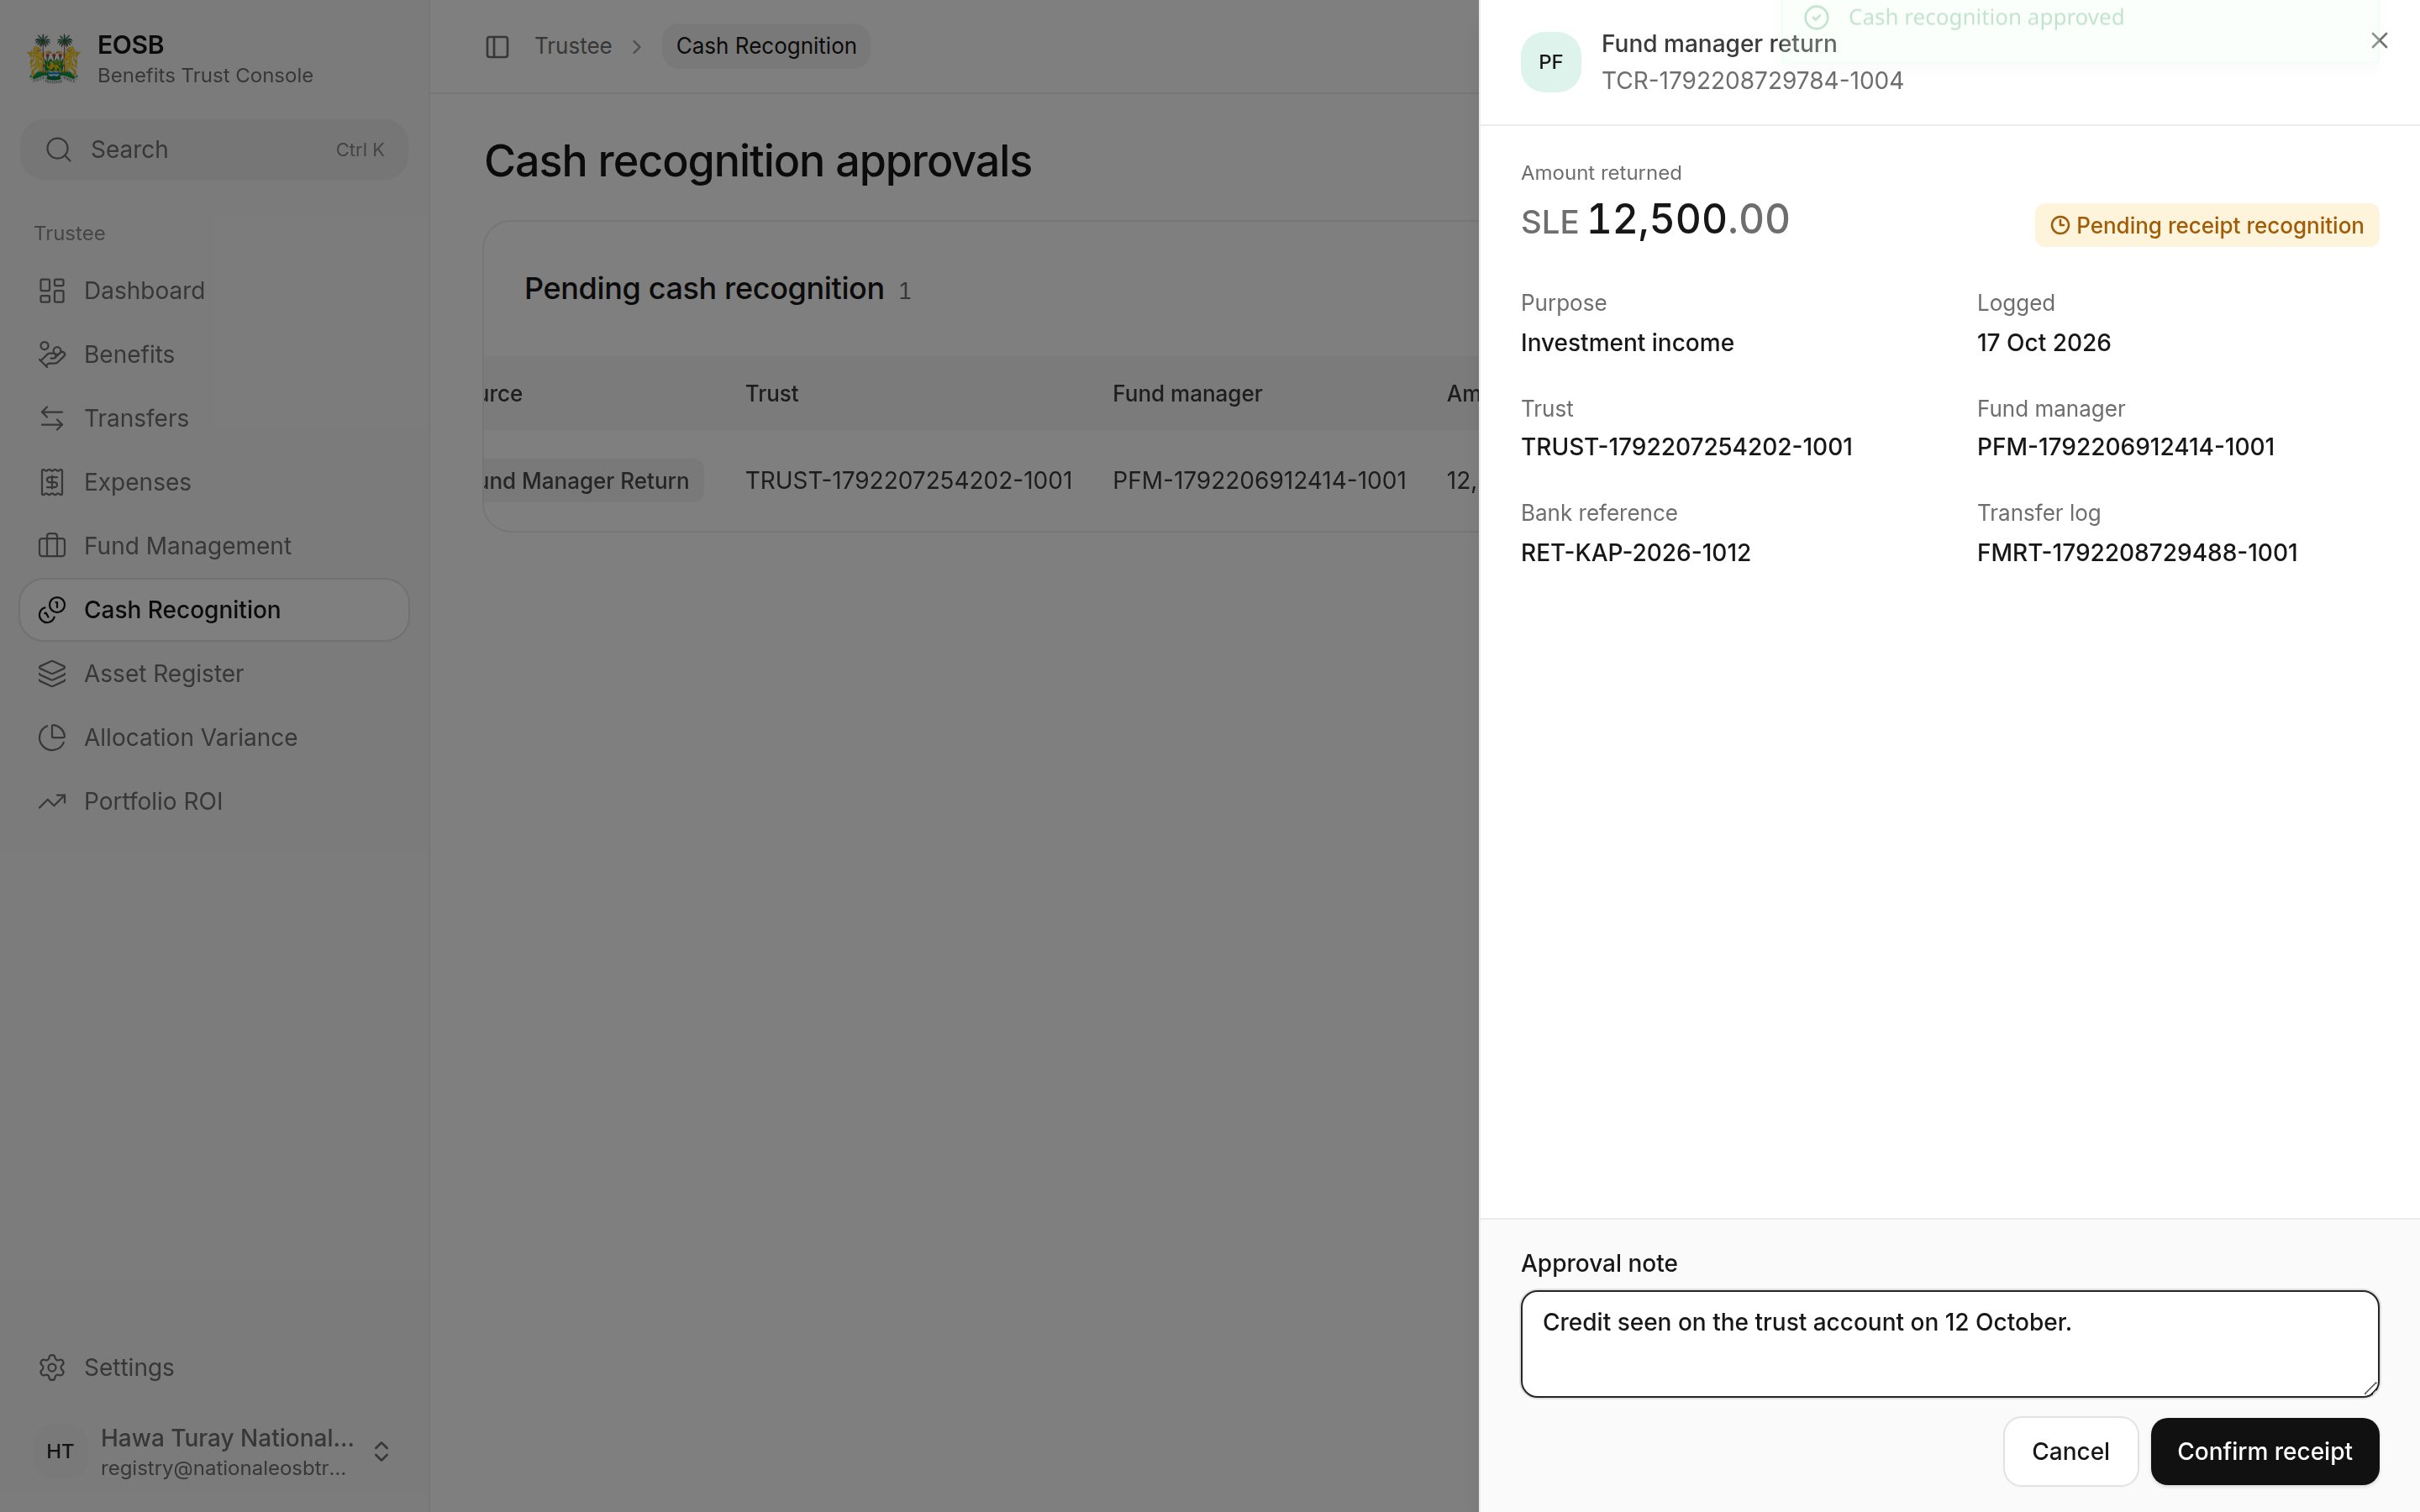
Fund manager return

Check the credit on the trust bank statement, then select Confirm receipt or Reject receipt (with a reason).
Approval note: Credit seen on the trust account on 12 October, and Confirm receipt

Confirming receipt

When nothing is waiting, the page says Nothing to review.

What happens next

  • An approved recognition adds the recognised amount to the fund manager’s cash for the trust and closes the difference.
  • A confirmed return puts the money back in the trust, ready for benefit payments or another transfer.
  • A rejected one is not booked; the fund manager has to correct it.
Next: expenses and budgets.